
Care for Your Dollars – A Cash Balance Case Study
Dr. Livingston and Dr. Kildare, partners in a medical practice, came to us looking for help. Dr. Livingston had owned the practice for several years, while Dr. Kildare was a new owner. Both were interested in accumulating wealth for retirement, but they recognized that they were in different places in life.
Scenario 1
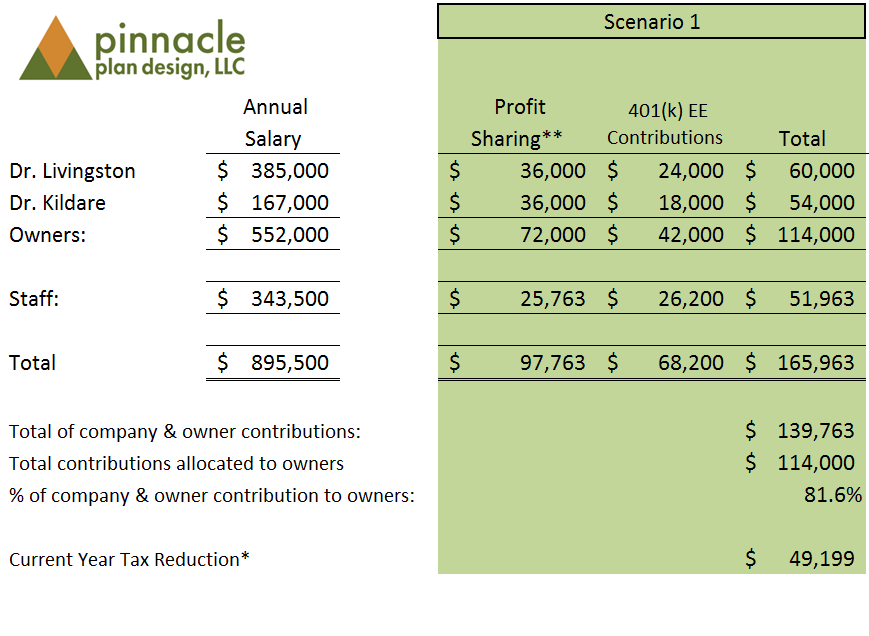
We started our discussion with their existing Safe Harbor 401(k) profit sharing plan. By defining each individual as their own “group” we could allocate the maximum to both Dr. Livingston and Dr. Kildare. Since Dr. Livingston is over 50 years old, he is allowed a catch-up contribution of $6,000. The cost is 7.5% of compensation to the employees. This resulted in 81.6% of all employer money allocated to Dr. Livingston and Dr. Kildare.
Safe Harbor 401(k) Profit Sharing Plan
Scenario 2
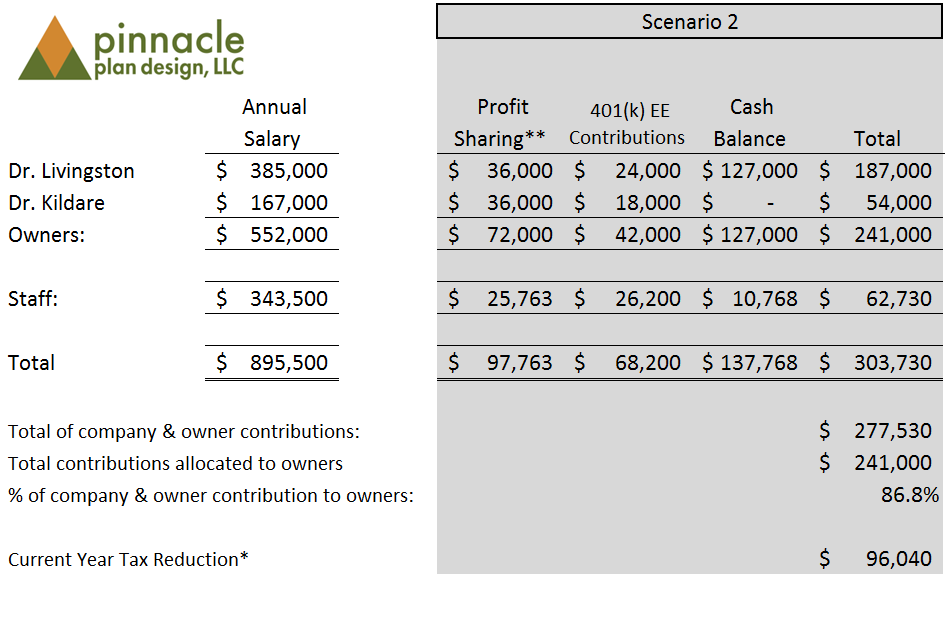
Dr. Livingston really wants to put away more than the defined contribution maximum. Based on the demographics, we found that we could add a cash balance plan and define a contribution credit of the lesser of $127,000 or 50% of compensation for Dr. Livingston. Along with this, we have a cash balance credit for the staff of the lesser of $1,500 or 3.5% of compensation (total cost is just under $10,800). At this point, we did not include Dr. Kildare in the cash balance plan. This resulted in 86.8% of all employer money allocated to Dr. Livingston and Dr. Kildare.
Added Cash Balance Plan
Scenario 3
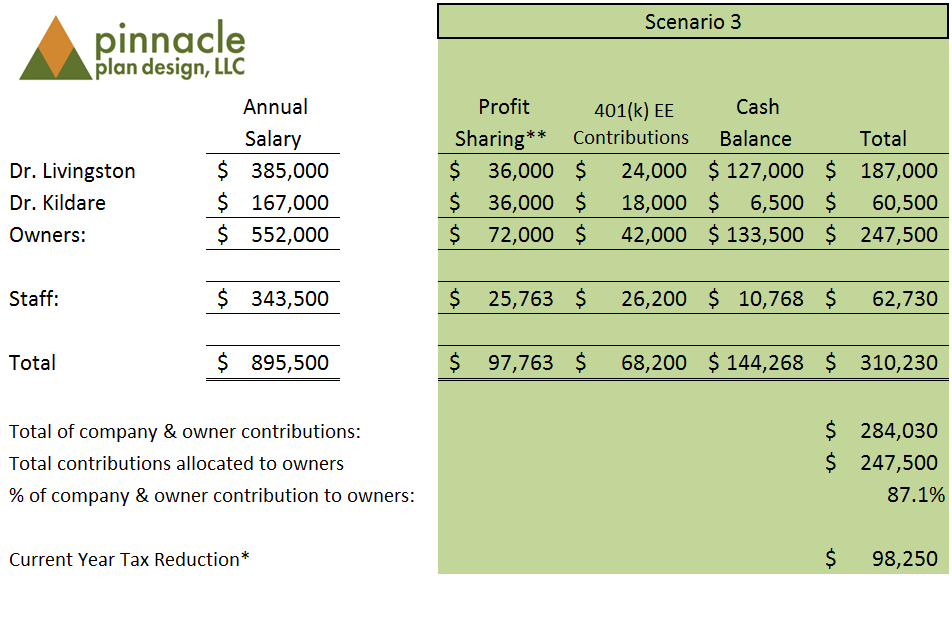
Finally, Dr. Kildare decides that he wants to participate in the cash balance plan. Without further increasing the staff cost we find that we can define a contribution for him of the lesser of $6,500 or 4% of compensation. This resulted in 87.1% of all employer money allocated to Dr. Livingston and Dr. Kildare.
Both Owners in Cash Balance Plan
Dr. Livingston and Dr. Kildare are very happy with the progression of their plan design. Dr. Kildare understands that if he wants to cut back his contributions in a given year, he may simply reduce his deferrals or his profit sharing allocation.
Every company is unique, as are their retirement needs. Our consultants at Pinnacle Plan Design will sit down with you and will listen to your questions, desires, and concerns and will design a plan or plans that will best suit your needs. Please contact us for more information.
* Assumes 34% company tax rate & 38% owner individual tax rate
** Profit Sharing amounts include safe harbor non-elective contributions
Plan Designs are for illustration purposes only
Consultation Request
Contact us for a consultation about your retirement plan options.
"*" indicates required fields